Sep 17, 2026
Why a Condo Could Be the Smartest First Home in Austin
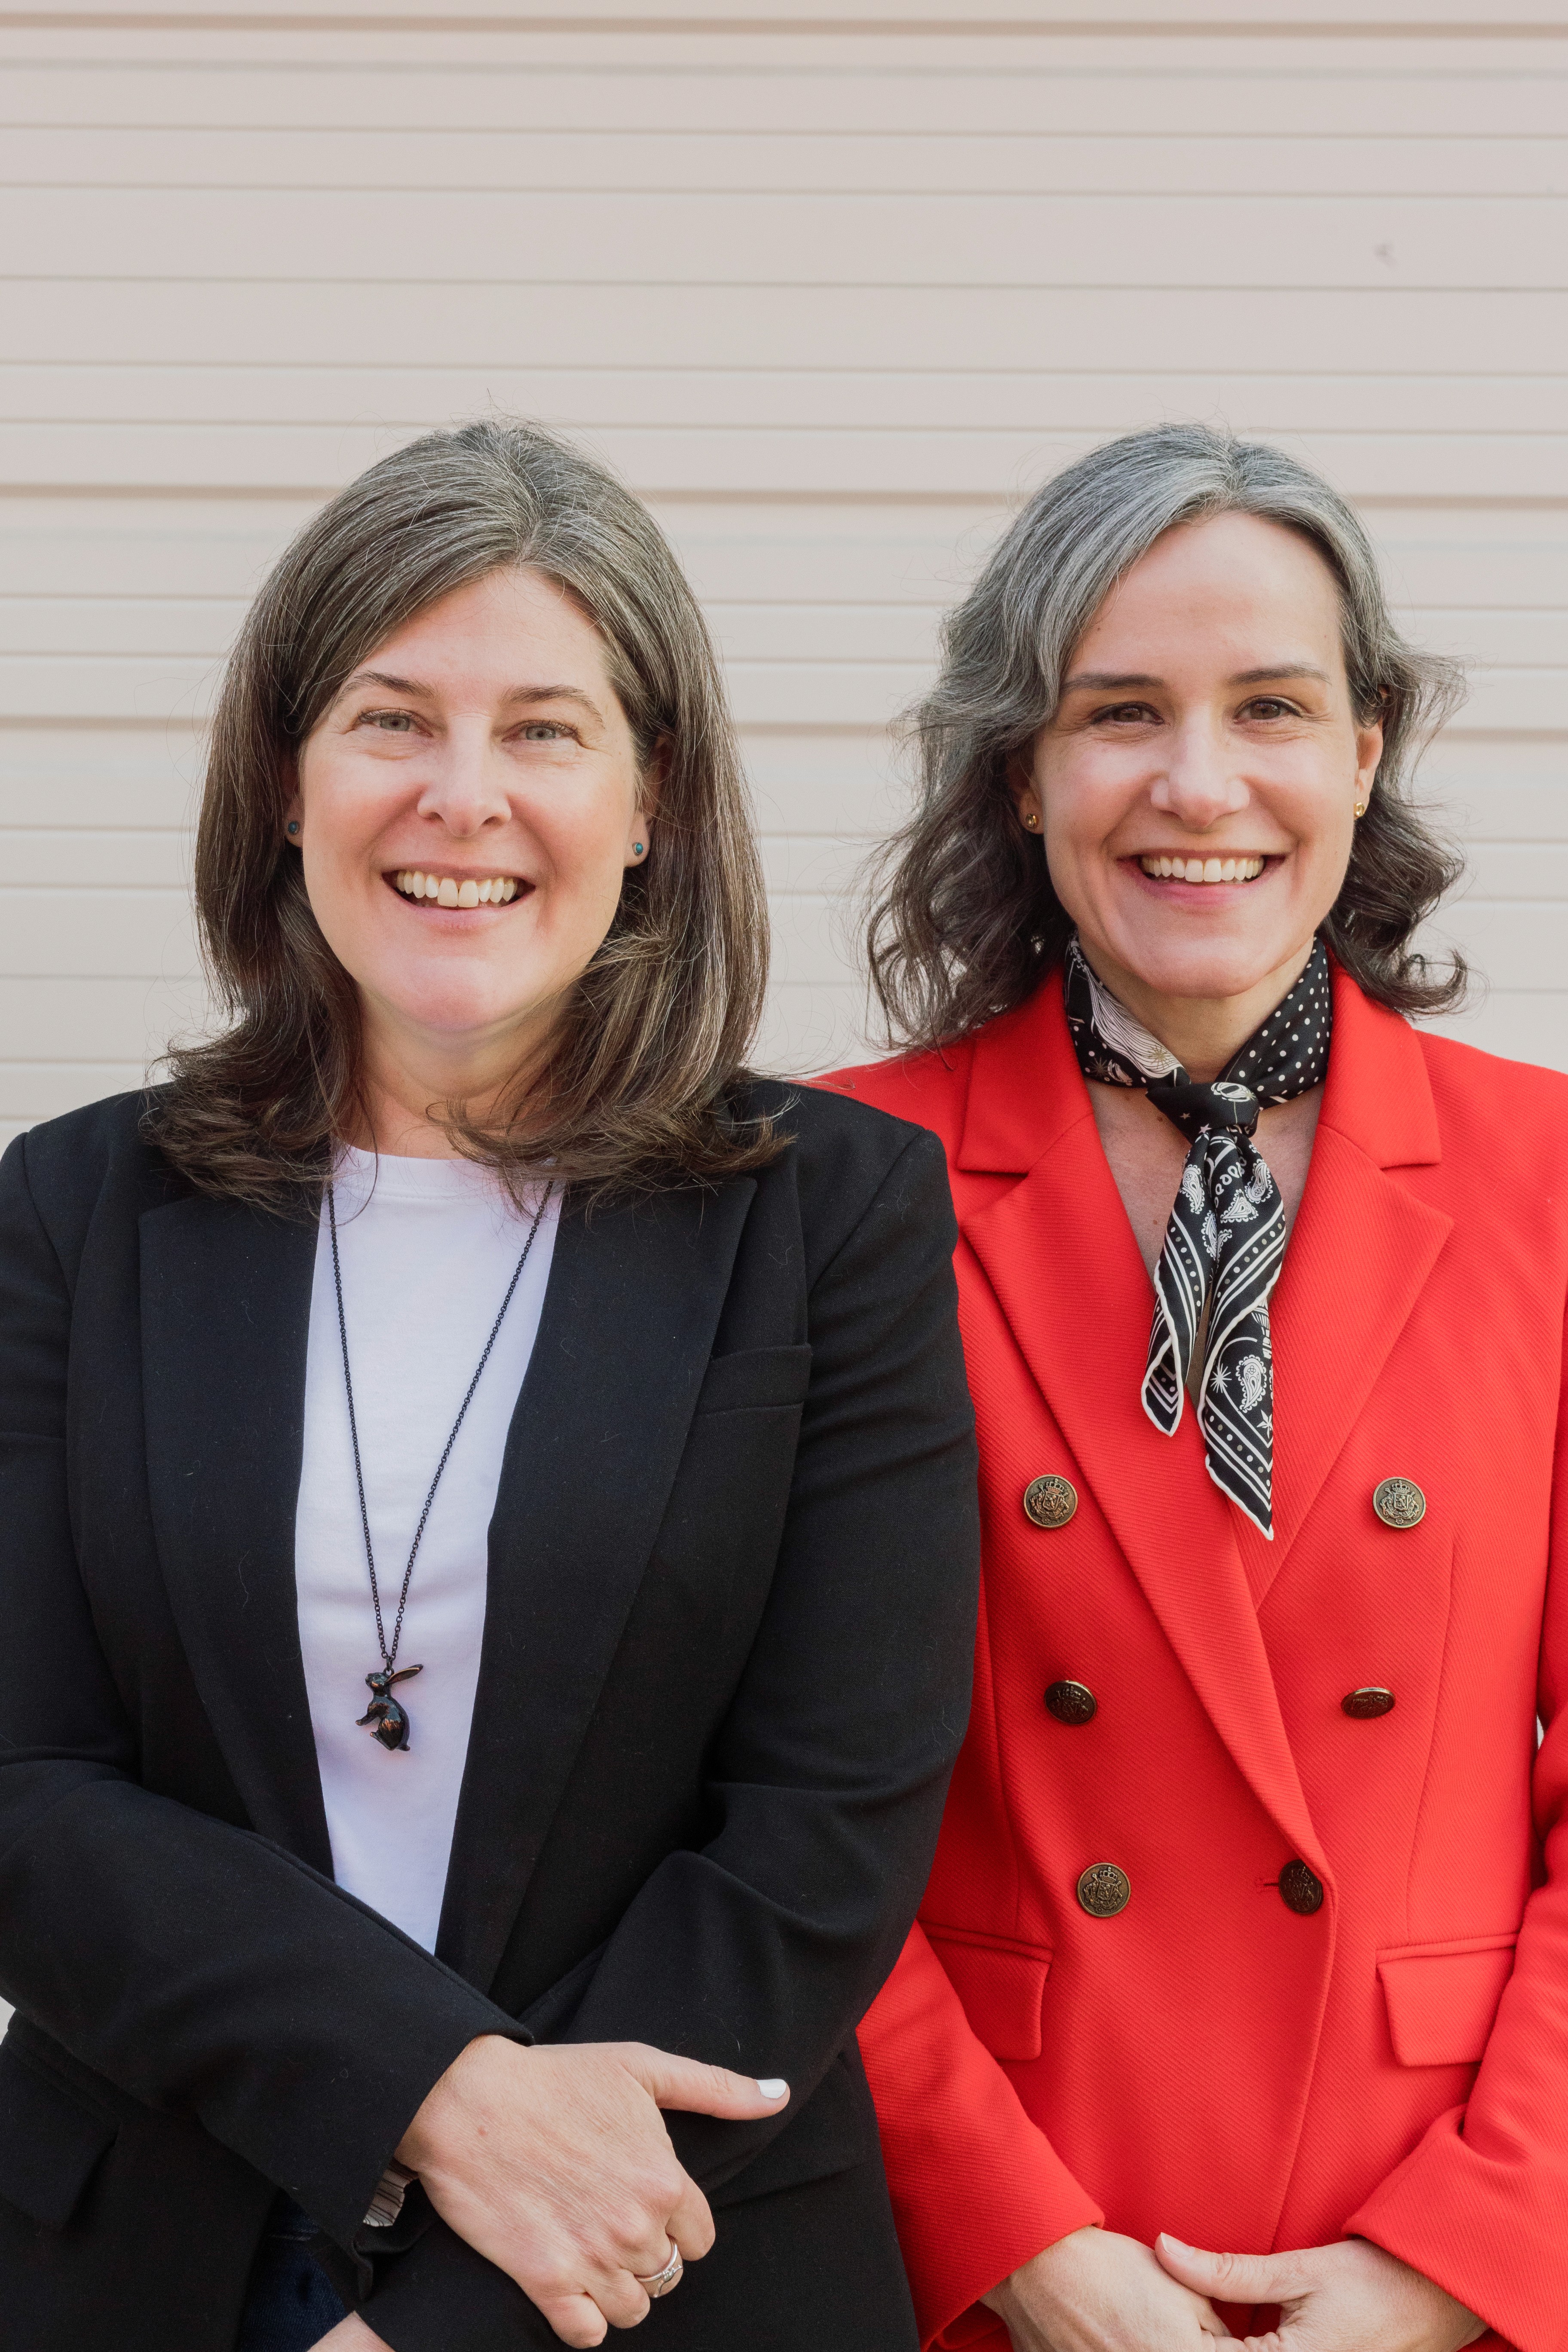
A condo can be the fastest way into Austin homeownership, and Mueller Residential Group doesn't treat that as a fallback plan. Principal REALTOR® Kathy Sokolic bought her own first Austin home as a two-bedroom, two-bath condo near South Congress and Stassney, and it did exactly what a first home is supposed to do: it got her started.
A first home doesn't have to be a forever home. It has to work for the buyer right now, and ideally point toward whatever comes next.
Kathy had a roommate who helped cover the mortgage, remodeled the place once she was convinced she'd live there forever, and moved on anyway when life changed. When she was ready for her next home, she sold that condo for a profit and rolled the equity into her next property. That first condo became her foothold in Austin real estate, and it's a large part of why our team encourages first-time buyers to give condos a serious look.
A Different Price Point in a City That Keeps Climbing
Single-family home prices in Austin have priced plenty of first-time buyers out of the conversation entirely. Expanding a search to condos opens up a different set of options than most buyers expect. Kathy recently toured a two-bedroom, two-bath condo listed under $200,000, inside Austin city limits. Not every condo carries that price tag, and price is only one part of what a buyer can actually afford, but a limited budget shouldn't rule out homeownership in Austin before condos are part of the conversation.
Splitting the Mortgage With a Roommate
A second bedroom means a buyer doesn't have to carry the mortgage alone. Kathy's roommate in her first condo covered a share of the cost, and that arrangement is part of why homeownership worked on her timeline, all while she kept her own bedroom, bathroom and private space. For the right buyer, a spare room flexes with life: a roommate now, an office later, or eventually a room that's simply theirs again once circumstances change.
Buyers Own the Home, Not Every Repair
Condo associations typically take at least some exterior and common-area maintenance off an owner's plate. Roofs, siding and landscaping come standard with a single-family home, and a condo association absorbs a meaningful share of those costs and decisions instead, depending on the community. HOA dues fund that coverage, and those dues belong in the affordability math from day one, even as they free an owner from personally managing certain big-ticket repairs.
Amenities Worth Sharing
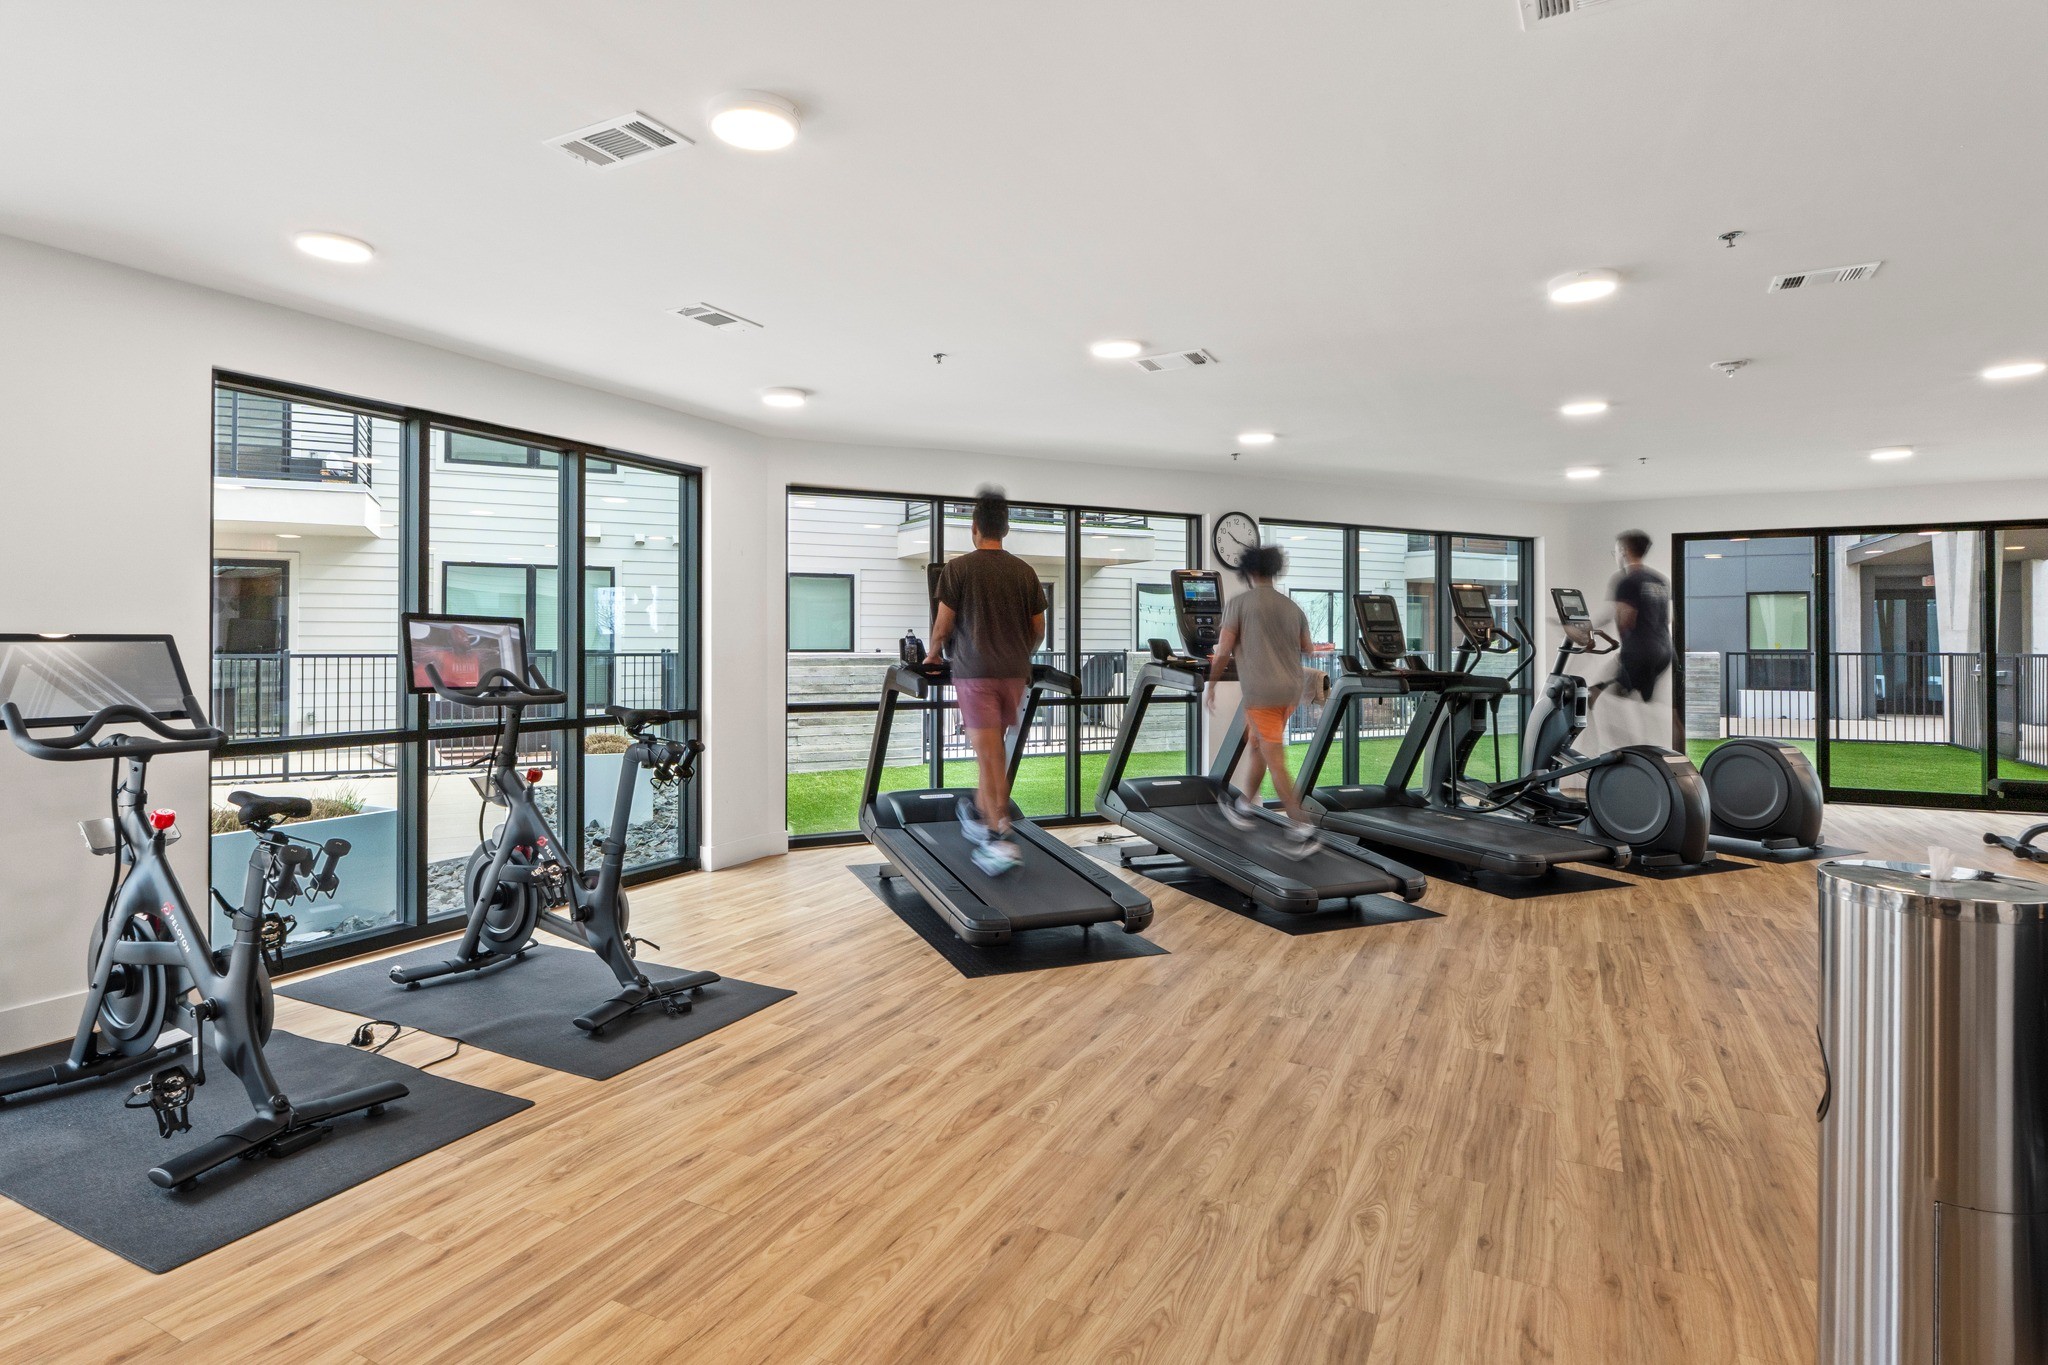
Pools, fitness centers and shared outdoor space often come standard with a condo, at a fraction of what it costs to build privately. Parking looks different from one community to the next: some offer open lots, others assign spaces, and a few include carports or garages, so this is worth mapping to a buyer's actual priorities before making an offer.
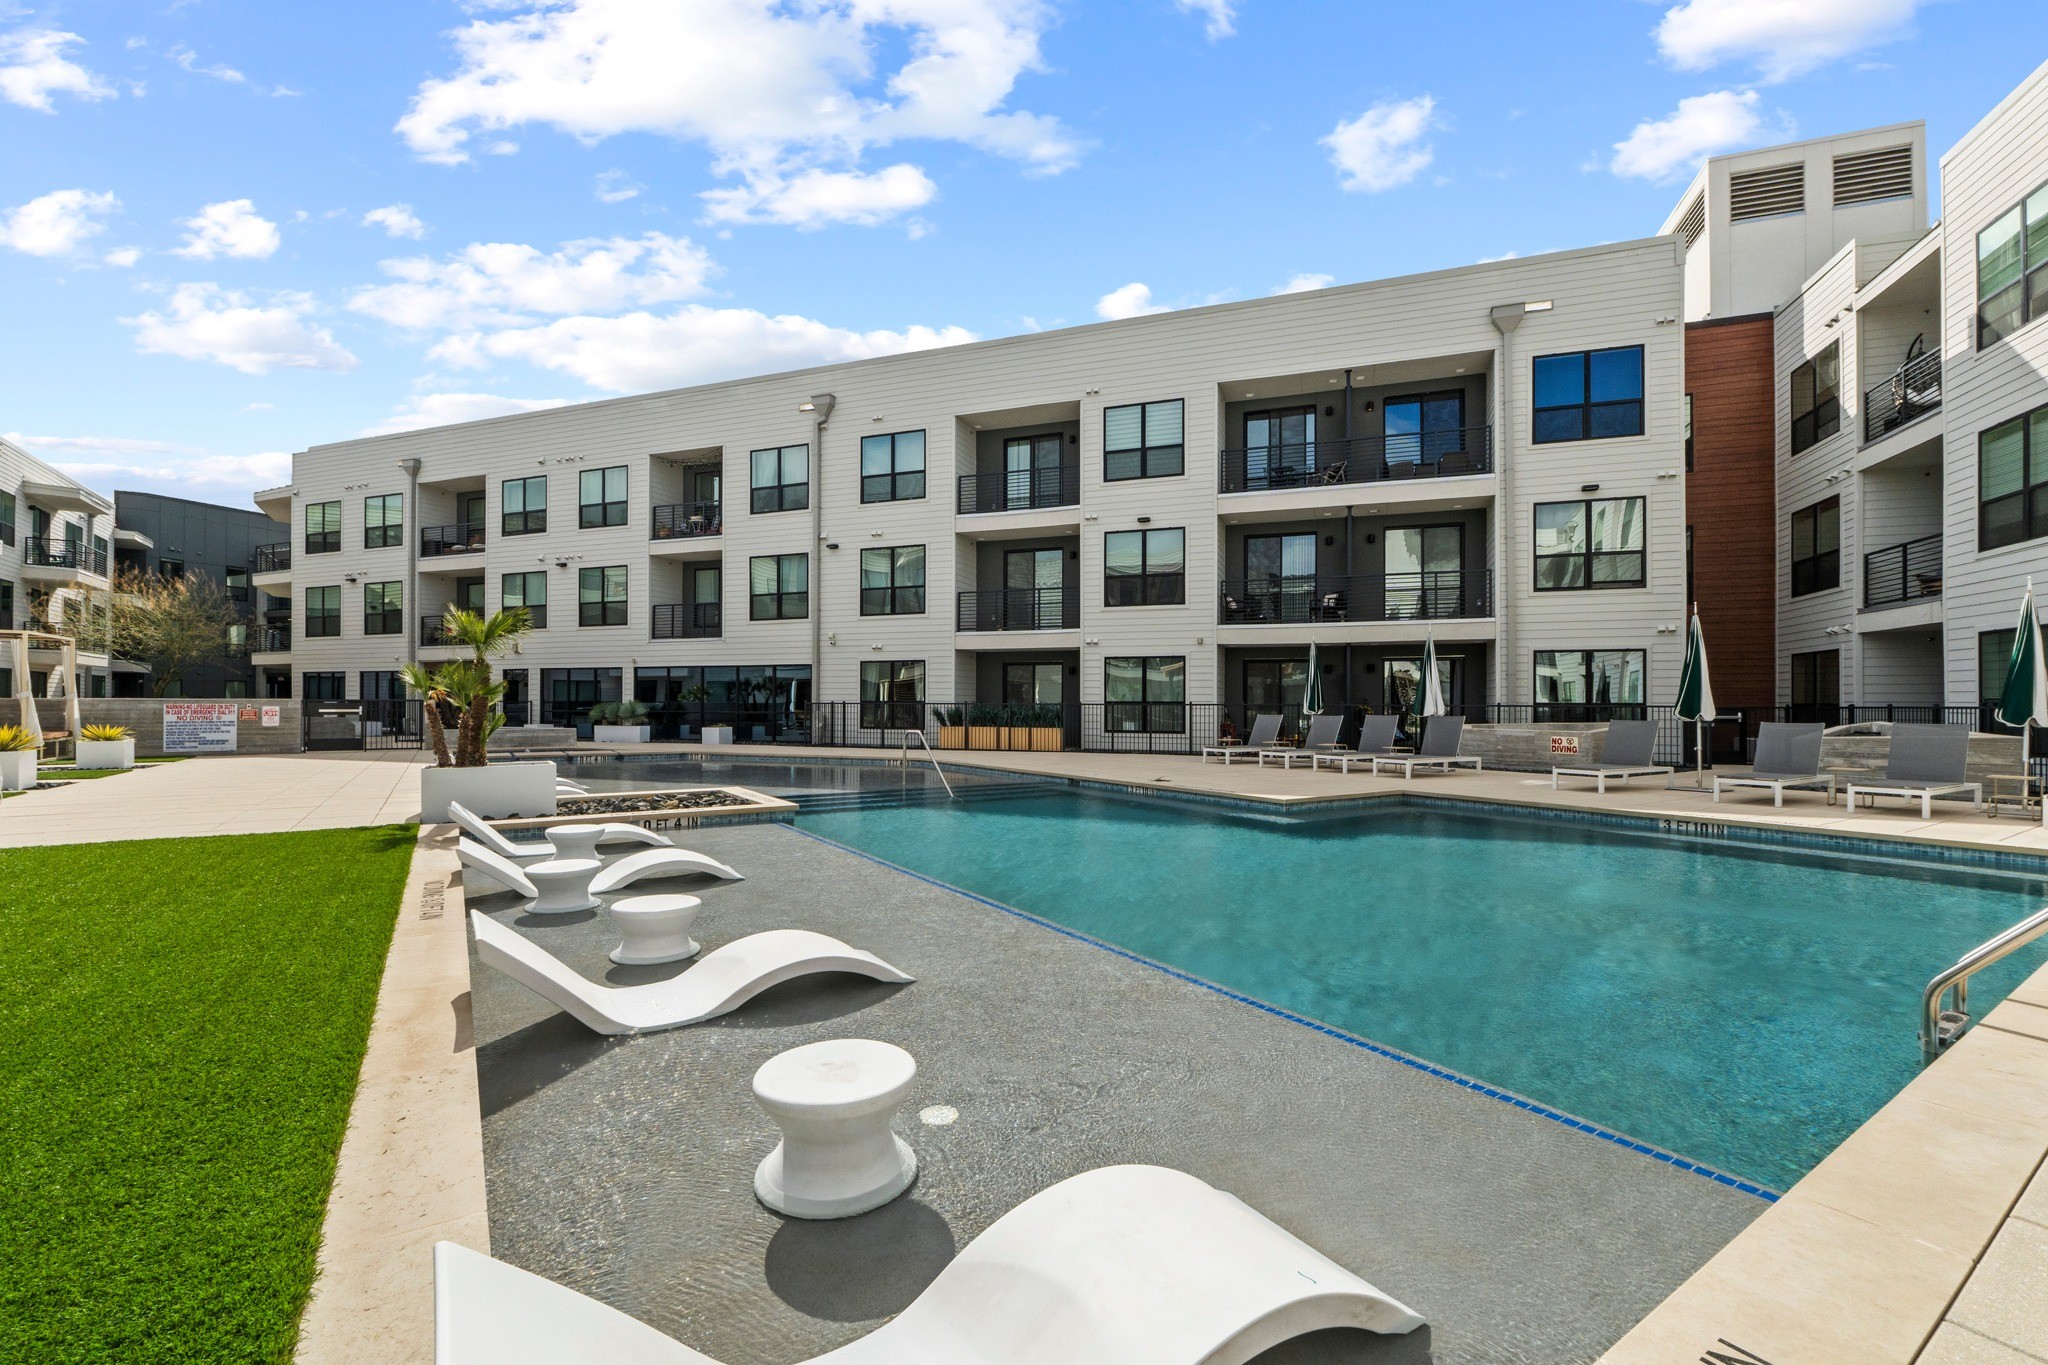
One Mueller condo the team recently listed, at 1320 Robert Browning St. #408, came with downtown views and trail access built into the price, the kind of lifestyle upgrade that's harder to find at a comparable cost in a standalone home.
A First Home Is Allowed to Be a First Step
Buyers aren't signing up to live in a first home for the next thirty years. Kathy's condo worked for the stage of life she was in, and when that stage ended, she sold it and moved on with the equity in hand. Depending on the property and the buyer's circumstances, that can mean selling later and rolling proceeds into the next home, or holding the condo as a rental instead. Neither path is guaranteed, since values shift and some communities restrict rentals, but a first purchase built the right way creates options down the road.
Some Mueller residents make this exact move without ever leaving the neighborhood; from a condo to a townhome to 55+ living, all within one community.
What Mueller Residential Group Checks First
A low sticker price on a condo is not automatically a good deal. HOA dues and what they actually cover need a close look, along with the association's finances, reserves and any pending special assessments. Insurance responsibilities, rental restrictions, parking rules and pet policies all shape day-to-day life in the property, so our team reviews each one before a client falls for a listing. Financing a condo can also work differently than financing a single-family home, which is why we recommend looping in a lender early in the process.
None of this is about finding the cheapest condo in Austin. It's about finding the one that fits a buyer's budget, lifestyle and next move.
So, Should a First Home Be a Condo?
A condo won't be the right first home for every buyer, but affordability alone shouldn't rule out the conversation. The right condo can offer a lower barrier to entry, lighter maintenance, useful amenities and room to change course later.
For the bigger picture on where Austin prices are headed, Mueller Residential Group's Mueller Market Update videos track the numbers month by month.
It worked exactly that way for Kathy: a two-bedroom condo, a roommate she loved living with, and eventually a launchpad into her next home. A first home doesn't need to be the dream home. It just needs to be a genuinely good first move.
Condo FAQ's
Is buying a condo a good idea for a first-time buyer in Austin?
For many first-time buyers, yes. A condo typically costs less upfront than a comparable single-family home, and it can create a realistic entry point in a market where prices have climbed well past what an entry-level buyer expects to pay.
What's the difference between an HOA fee and a mortgage payment?
The mortgage payment covers the loan on the property itself. The HOA fee is a separate, recurring cost that funds shared maintenance, insurance on common areas, and amenities, and it needs to be added to the total monthly housing cost when calculating affordability.
Can a condo be rented out later if the owner decides to move?
It depends entirely on the association. Some condo communities allow rentals freely, others cap the number of units that can be leased at once, and a few restrict rentals altogether, so this is one of the first things our team checks before a client buys if renting is part of the long-term plan.
Is financing a condo different from financing a single-family home?
Often, yes. Lenders may look closely at the condo association's finances, owner-occupancy rate and insurance coverage before approving a loan, which is why looping in a lender early, before falling for a specific listing, matters.
What should buyers look for in an HOA's financial health?
Ask for the association's reserve study, current reserve balance and any pending or recent special assessments. An association with healthy reserves and no looming assessments is a far safer bet than one running month to month.
Do all condos come with amenities like a pool or gym?
No, amenities vary widely by community. Some buildings include a pool, fitness center and shared outdoor space in the HOA dues, while others offer none of that, so confirming exactly what the dues cover matters before comparing price tags across communities.
What happens to exterior maintenance responsibilities in a condo?
The association typically handles at least some exterior and common-area upkeep, which can include the roof, siding, landscaping and shared structures, depending on the community's governing documents. The owner's personal maintenance list usually shrinks, but it rarely disappears completely.
Are condos a good investment compared to single-family homes?
Condos can build equity just like single-family homes, though appreciation and resale demand can differ by community and by how many units are owner-occupied versus rented. Reviewing recent comparable sales in each building is a necessary step before making a call on any specific property.
What pet and parking policies should buyers ask about before purchasing?
Ask about breed or weight restrictions, pet fees, and how many pets are allowed per unit, along with whether parking is assigned, open or covered. These details shape daily life in the property far more than most buyers expect going in.
How can a buyer tell if a condo is priced fairly?
Compare recent sales of similar units in the same building or community, factor the HOA dues into the total monthly cost, and confirm the association isn't carrying a special assessment that could inflate the true price. A low list price paired with high dues or a pending assessment isn't the deal it appears to be on paper.